


This guide helps you to compare some of the most popular ACH payment processors in the market, analyzing each for cost, speed, features and support, so you can discover who adds the best value for your business.
TL;DR
- Helcim is the lowest-cost ACH processor that also handles cards and invoicing in one account: 0.5% + 25¢ per payment, capped at $6, with no monthly fee and free invoicing. Forbes Advisor named it “Best for Lowest ACH Payment Rates” (2026).
- GoCardless Standard is the cheapest ACH payment processor per payment (20¢ less than Helcim), but it doesn’t accept cards and has no built-in invoicing.
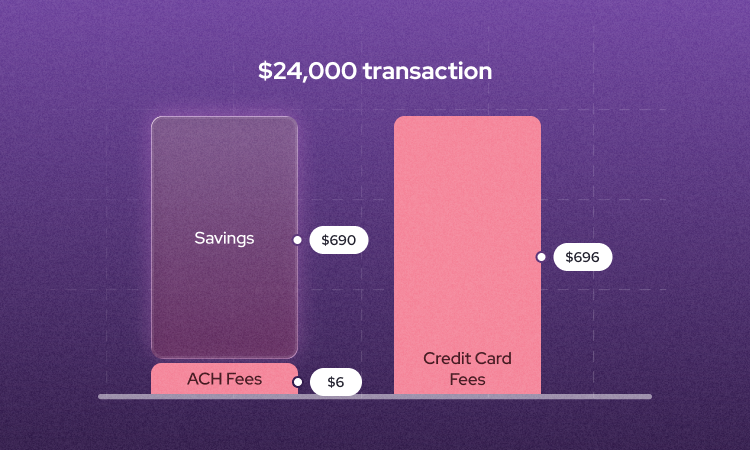
- Square, QuickBooks and Finix charge 1% with no cap on their standard plans, so a $10,000 payment costs $100, compared with $6 at Helcim.
- QuickBooks funds fastest (next business day), and Stripe and Finix suit businesses building payments into their own website, app or software platform.
How did we choose the best ACH payment processors?
When analyzing the market for the best overall ACH payment processor, we looked at cost, speed, features and support.
Here’s how each of these aspects breaks down:
- Cost: ACH rate, fee cap, failed or returned payment fees, monthly fees and add-ons.
- Speed: Time to funds deposited in your bank account.
- Features: Recurring ACH billing, debit and credit card acceptance, email and SMS payment requests, built-in invoicing, branded payment pages.
- Support: Accessible and responsive human support.
We took all of these factors into account because ranking who is “best” is not synonymous with who is simply the “cheapest,” or “fastest” (although those help). A true “best ranking” needs to include all of the factors that a business looks for in their ACH provider, including helping you to plainly see benefits and the pitfalls that so many only discover after sign-up (Hint: of course we looked at hidden fees).
The information in this comparison is sourced from each ACH payment provider’s websites and focuses on published U.S. pricing, as of October 2026. And yes (just to jump in on what you’re already thinking), Helcim is ranking itself in this comparison. In the spirit of the transparency we value so much, you’ll see where Helcim both wins and loses against the competition.
Providers were included if they:
- Collect ACH payments from customers
- Publish U.S. ACH pricing
- Are ranked by a major independent review, or
- Are an option that U.S. businesses commonly compare
What is the best ACH payment processor in 2026?
U.S. pricing from each provider's published pages, checked October 15, 2026.
| Helcim | GoCardless | Stripe | Square | QuickBooks Payments | Finix | |
|---|---|---|---|---|---|---|
| Best for | Lowest-cost all-in-one: ACH, credit cards and invoicing in one account | Lowest per-payment rate for bank payments only | Businesses building payments into their own website or app | Businesses that want ACH inside a Square point-of-sale setup | Fastest funding for businesses already on QuickBooks | Software platforms and high-volume businesses with a tech team |
| ACH rate | 0.5% + 25¢ for $25,000 and below. Excess of $25,000 gets charged at 0.05%. | 0.5% + 5¢¹ | 0.8% | 1% ($1 min) | 1% | 1% + 25¢ |
| Time to funds² | 3–5 business days | 3 business days | About 4 business days | 2–3 business days | Next business day | 5+ business days |
| Fee cap per payment | $6 | $5 | $5 | None³ | None⁴ | $10⁷ |
| Failed or returned payment fee | $5 | $5 | $4 | $0, per Square | Not published | $5 |
| Monthly fee | $0 | $0 | $0 | $0 (Free plan) | $0 with QuickBooks Free for 2 invoices/mo)); unlimited invoicing from $38/mo; recurring billing from $85/mo | $250/mo membership |
| Recurring ACH billing | Yes, +0.4% on top of the ACH fee (the 0.4% isn’t capped) | Yes | Yes, +0.7% via Billing | Yes | Yes, Essentials plan ($85/mo) and up⁵ | Yes, +0.4% |
| Also accepts debit and credit cards | Yes | No | Yes | Yes | Yes | Yes |
| Email and SMS payment requests | Email, SMS, and Payment Links | Email only | Email only | Email and SMS | Email only | Payment links you send yourself |
| Built-in invoicing | Yes, free | No | Yes, +0.4% per paid invoice | Yes, free | Yes; Free plan limited to 2 invoices/mo | Yes, +0.4% |
| Branded payment pages | Included, free | Logo and colors free; custom pages $50/mo⁶ | Included; custom domain $10/mo | Logo and brand color | Logo, colors and fonts | Logo and colors on payment link pages |
| Human support | Real people by phone, email and ticket; public phone line | Phone and web form; chatbot first | 24/7 phone, chat and email | Phone not guaranteed for all merchants | Phone and chat, weekdays | Email only; no phone line (callbacks on request) |
¹ Standard plan. Advanced (0.75% + 5¢, $6.25 cap) and Pro (0.9% + 5¢, $7 cap) cost more.
² Providers measure time to funds from different points: Helcim from settlement (batch close), GoCardless from the charge date, and Square to your Square account.
³ Free plan. Square’s Plus and Premium plans cap ACH fees at $10.
⁴ For accounts that added QuickBooks Payments on or after Sept. 5, 2023.
⁵ The customer signs a bank transfer authorization, then QuickBooks charges their bank account on the schedule you set. Standard 1% ACH fee applies.
⁶ Advanced and Pro plans only. Showing your business name on customers’ bank statements costs another $25/mo.
⁷ Finix caps the 1% portion at $10. Its pricing page doesn’t say whether the 25¢ fee falls under the cap.
All pricing is from each provider’s published U.S. pages as of October 15, 2026. Stripe also charges $1.50 per instant bank verification. Helcim’s $6 cap applies to its 0.5% + 25¢ ACH fee on payments under $25,000. The 0.4% recurring fee is charged on top and isn’t capped.
Here’s how each provider compares, including who it’s best for and what to watch out for if you sign up:
Helcim: Best for lowest-cost all-in-one
Helcim stands out as a high-value ACH payment processor for businesses that want to create an easy, low-cost ACH payment experience but also want to offer their customers other ways to pay, like cards and digital wallets (e.g. Apple Pay and Google Pay). Your customers see card and ACH options on the same Helcim payment link, so they can choose how to pay in one checkout.
Unlike other providers, Helcim doesn’t move you onto a paid plan once you reach a higher volume of transactions, the way these providers do: QuickBooks ($38/mo) SquarePlus ($85/mo) or Finix ($250/mo). Plus, card payments use interchange-plus pricing with built-in volume discounts, so your card costs drop as your volume grows.
For ACH payments, having the ability to accept cards is a big plus as you can set a card as backup in case an ACH payment fails. Plus, you also get free Helcim invoicing, free branded payment pages, email and SMS payment requests, a Helcim recurring payment tool, and a customer management tool to store ACH authorization form securely. And when you need support, you get real people by phone, email and ticket.
Pricing: Helcim ACH payment costs 0.5% + 25¢ per transaction, capped at $6 on payments under $25,000 and costs extra 0.05% on the amount over $25,000. Helcim charges $0 monthly and $5 return fee. Recurring ACH adds 0.4% on top of the regular ACH fee, and the 0.4% isn’t capped.
What to watch out for: While Forbes Advisor named Helcim “Best for Lowest ACH Payment Rates,” Helcim is 20¢ more than GoCardless on one-time payments, and comes with additional fees on recurring payments (at 0.4% add-on for recurring payments, Helcim would be about $2.20 more on a $500 recurring payment). Additionally, funds take 3–5 business days to receive on average, so if you’re looking for an instant ACH payment processor, Helcim isn’t it (but to be fair, not many others can offer that kind of speed either). When speed matters, accept credit cards too. Helcim deposits card payments the next business morning.
GoCardless: Best for lowest per-payment rate
Dollar for dollar, GoCardless beats the competition as the cheapest ACH payment processor. GoCardless is a bank payment specialist that’s been built around pulling payments from customers’ accounts and it’s especially loved for businesses that have customers sign up for recurring payments, such as subscriptions, memberships, retainers and installment. GoCardless also delivers funds in just three business days and they offer the ability to add your logo and custom colors to your payment pages for free.
GoCardless’s customers love the way they’ve saved money on the platform. Oli Shaw-Latimer, Head of FinTech and Innovation at JustGiving says: “With Pay by Bank from GoCardless we've reduced the cost per payment by 70-80%.”
Pricing: GoCardless ACH transaction fee fluctuates by monthly plans: Standard costs 0.5% + 5¢ ($5 cap), Advanced costs 0.75% + 5¢ ($6.25 cap), Pro costs 0.9% + 5¢ ($7 cap). Similar to Helcim, GoCardless costs $0 monthly for basic ACH payment processing. It charges a $5 failed payment fee.
What to watch out for: While GoCardless is a solid choice for ACH payments, the name literally gives away the fact that it does not offer paying via cards (so if an ACH payment fails, there’s no card backup). Plus, if you want to go beyond a logo and custom colors for your payment pages, the costs do creep up. GoCardless Custom Pages cost $50/mo and adding your business name on statements costs $25/mo. And if you value getting to a person quickly, GoCardless asks you to try its chatbot first and uses a web form instead of a support email, though it does list a U.S. phone number.
GoCardless also doesn’t offer native invoicing tools, so businesses have to use third-party invoicing tools like QuickBooks Online which cost extra per month. Besides, GoCardless payment requests can not be sent via SMS; in contrast, Helcim payment requests can be sent via both email and SMS.
Stripe: Best for businesses building payments into their own website or app
Users who love Stripe know it for its API, which enables businesses to integrate payment processing into their own website, app or software. While its versatility allows users to also use it without needing to write code, its features are designed to support custom payment integrations. Getting the most out of the platform happens when you either have code knowledge or have support from an in-house developer, freelancer or agency. This is why you’ll see Stripe used often by companies that are built on custom sites, like software and SaaS companies, ecommerce and subscription businesses, and platforms and marketplaces that take payments on behalf of other businesses.
Pricing: Stripe ACH payment processing fee is 0.8%, capped at $5. Similar to Helcim and GoCardless, Stripe charges $0 monthly fee. It charges a $4 fee per failed ACH transaction, and $1.50 per instant bank verification, so merchants pay an extra fee every time they sign a new customer.
What to watch out for: While Stripe wins on custom coding versatility, their recurring billing add-on fee of 0.7% is higher than the others. Plus, their instant bank verification fees charge $1.50 each time you add a new customer. This matters because those fees can stack up fast, and many of the businesses that would gravitate towards the customizations (SaaS, ecommerce and subscription businesses) are also more likely to sign new customers often while also offering subscriptions and memberships. Additionally, funds take about 4 business days to arrive, and new accounts wait about 7 days for their first payout.
ACH disputes also sting more with Stripe. On top of the dispute fee and the refunded payment, Stripe revokes your customer’s ACH authorization after their first dispute. Any future scheduled payments from that bank account, like recurring ACH, will fail until your customer signs a new authorization, and a second dispute gets the account blocked.
Learn more about Helcim vs Stripe.
Square: Best for businesses that want ACH inside a Square point-of-sale setup
Square is one of the most recognized payment processors for small to medium businesses thanks to the popularity of their in-person point-of-sale systems (card readers, registers, retail and restaurant software). ACH payments are offered through Square, mainly through Square invoices. For businesses who are already on Square, leveraging the platform that they already know and love for the times where someone wants the option to pay by ACH makes a lot of sense.
Plus, Square processes ACH payments quickly (2-3 business days) and unlike the competition, Square doesn’t charge a failed ACH payment fee, which is a nice bonus.
Pricing: Square ACH payment processing fee is 1% ($1 min), no cap on the Free plan. Square offers different subscription plans such as Plus ($49/mo) and Premium ($149/mo) that cap ACH at $10. It charges a $0 fee for failed ACH payments.
What to watch out for
If ACH payments are infrequent in your business, you may feel that it’s worth it to pay Square’s higher ACH fees simply for the convenience factor. However, businesses that have a large customer base who opt to pay by ACH can find themselves paying much more than if they had signed on with other ACH providers because Square’s ACH fee isn’t capped for Free plan. For example, with Square’s no cap on the Free plan, a $10,000 payment costs $100. With Helcim, that same payment would cost the business just $6. Even at $500, that’s $2.75 instead of $5, or $2,700 a year in savings on 100 payments a month. If this sounds like you but you love Square, you don’t have to stay on it for ACH. Compare what your monthly bank payments cost on Square’s uncapped 1% against a capped rate.
Learn more about Helcim vs Square.
QuickBooks Payments: Best for fastest funding
It’s hard not to know the name “QuickBooks.” The company has been around since the 1990s and has created a reliable reputation as a bookkeeping platform. So, it makes sense that QuickBooks would have a payment add-on built into their accounting software. Through QuickBooks Payments, when customers pay their QuickBooks invoices via ACH or card, the payments get recorded into your books automatically, making it highly practical.
But, it’s more than that: QuickBooks Payments also offers the fastest ACH payment processing of any competitor we analyzed. Like, lightning fast. QuickBooks ACH payments are received within the next business day.
Pricing: QuickBook ACH payment processing fee is 1%, no cap. Besides, its ACH return fee is not published.
What to watch out for: Remember the old adage that something can either be cheap, fast or high quality, but you can only get two of the three? With QuickBooks Payments, you get speed and quality bookkeeping, but those benefits will cost you. Since QuickBooks Payments runs inside QuickBooks’ accounting software, your QuickBooks plan is part of the cost. While the $0 QuickBooks Free plan allows 2 invoices a month, unlimited invoicing costs $38/mo and recurring billing needs the $85/mo plan. Unfortunately, those fees don’t buy you very robust support or features either. There’s no built-in texting, and support is only available on weekdays. Restrictions like this are some of the reasons why some businesses choose to use one software for bookkeeping, and another for payments. Helcim also integrates with QuickBooks Online, so a QuickBooks user can keep their accounting and still get capped ACH fees with no plan upgrade.
Learn more about Helcim vs QuickBooks Payments.
Finix: Best for software platforms and high-volume businesses with a tech team
If you’re scaling a B2B company that is building its own payment system and/or has to manage payments to sub-merchants (e.g. you run a booking app or a marketplace with hundreds of sellers), Finix is built for you. This platform gives you the essential building blocks to be able to easily sign up new merchants, process payments, send payouts and handle compliance paperwork. All you need is a developer on hand to help connect these blocks in code.
Pricing: Finix ACH payment processing fee is 1% (max $10) + 25¢. It also charges $250/mo for membership and $5 ACH return fee. Finix recurring billing and invoicing each add 0.4% extra fee per ACH transaction.
What to watch out for
Finix comes with a $250 monthly membership and a less-than-speedy processing timeline for ACH payments (5-business-day ACH hold). Plus, their support exists via email-only. Businesses that aren’t serving B2B audiences or scaling at Silicon Valley SaaS speed may find that Finix offers them too many of the wrong kinds of benefits, and is expensive on top of it all.
What are the average costs for accepting ACH payments?
The ACH payment processing fee you pay will depend on volume and the fee structure of the ACH processor you choose. For instance, ACH processors tend to charge between 0.5% and 1% per ACH payment on average (sometimes plus a small fixed fee), with some capping the fee, and others offering no cap at all.
Plus, costs for accepting ACH payments can go beyond processing fees and include failed and returned payment fees, monthly and add-on fees and more (we go into those hidden fees below).
How do fee structures affect what you pay for ACH?
ACH processors use a few different fee structures including percentages (with and without caps), fixed fees and monthly fees, and each one changes how your costs grow as payments get bigger:
- Percentage with a cap: you pay a percentage of each payment until the fee hits a maximum (Helcim, GoCardless, Stripe and Finix).
- Percentage with no cap: the fee keeps growing with the payment size (Square’s Free plan and QuickBooks).
- Small fixed fee: some providers add a flat amount to every payment on top of the percentage, like Helcim’s 25¢ or GoCardless’s 5¢.
- Monthly fees: some charge a plan or membership fee on top of per-payment fees (QuickBooks, Square Plus and Finix).
Here’s how different fee types can impact the size of the fee you could pay, depending on the processor you choose:
| Payment size | Lowest | Median | Highest |
|---|---|---|---|
| $500 | $2.55 (GoCardless) | $4.50 | $5.25 (Finix) |
| $2,000 | $5.00 (GoCardless, Stripe) | $8.13 | $20.00 (Square, QuickBooks) |
Our calculation, based on the six providers’ published rates.
What are the hidden fees for accepting ACH payments?
The hidden fees for accepting ACH payments fall into three groups: per-payment fees (returns, uncapped percentages, bank verification and account-update notices), account fees (monthly plans, paid add-ons and charges for faster deposits), and cash-flow costs from payout holds.
Here’s what to know about each.
Per-payment fees
Per-payment fees are charged on each payment, so they accumulate as your ACH payment volume increases.
1. Return and failed payment fees: When an ACH payment fails or gets returned (e.g. if a customer flags the payment as unauthorized with their bank), you’ll get charged. These fees tend to be $4–$5 at most providers. Square charges $0, and QuickBooks doesn’t publish its fee. Unlike a card chargeback, an ACH return can’t be won back.
2. Uncapped percentages: As your payment volume and/or amount(s) increase, so do the fees you’ll pay. For example, a 1% uncapped rate means a $100 fee on a $10,000 payment.
3. Bank account verification fees: When you set up a new customer on ACH payments, their bank account will need to be verified, and this isn’t always free. For instance:
- Stripe charges $1.50 per instant bank verification.
- Finix charges $0.55 per ACH validation, or $3.00 through Plaid.
4. Notice of change fees: When a customer’s bank sends updated account details, you can end up paying for this too. For example, Finix charges $3.00 per notice.
Account fees
Account fee charges apply to your account or plan, whether or not you process many payments:
1. Monthly and plan fees, including features locked behind a plan: These plans and fees vary greatly by provider. For example:
- If you use Square as your ACH payment processor, you’ll need to upgrade your plan if you want to cap your per-transaction fees. Square Plus costs $49/mo, and only Plus or Premium caps ACH at $10.
- QuickBooks’ Free plan allows 2 invoices a month. Unlimited invoicing costs $38/mo, and recurring billing needs the $85/mo plan.
- Finix charges a $250/mo membership.
2. Add-ons for features you’d assume are included: Many businesses sign on with an ACH payments provider assuming they’ll be able to conduct business as normal without fees, but this isn’t always the case. For example:
- Stripe adds 0.7% for recurring and 0.4% per paid invoice, and charges $10/mo for a custom domain.
- Finix adds 0.4% each for recurring and invoicing.
- GoCardless charges $50/mo for custom payment pages and $25/mo to show your business name on customers’ bank statements.
- Helcim adds 0.4% for recurring.
3. Paying for speed: ACH payments are notoriously slower than other methods, but to speed up the process will usually cost you. For example, Finix charges 1.2% + 25¢ instead of its standard 1% + 25¢ (max $10) if you want to expedite ACH payment from its standard 5 business days to two-day ACH. Its instant payouts cost 1.5% of the amount.

Cash-flow costs
Cash-flow costs, via holds and slow funding, don’t show up as a fee, but they do affect when you can use your money. For example, Finix holds ACH payments for 5 business days by default, and many processors hold a new merchant’s first payouts for longer (with Helcim, this can be up to 7 business days).
How to choose an ACH payment processor
Choosing an ACH payment processor depends on your budget, how fast you need to receive payments, whether or not you value also offering versatile billing options (invoicing, email, SMS, credit card availability), and whether or not you need other options and customizability, such as adding your branding to payment pages and invoices.
How fast do you need to receive payments?
ACH payments take longer than other forms of payment to arrive in your bank account, so for businesses that are used to relying on speedy receivables to operate (e.g. contractors, wholesalers, events and hospitality), you might opt to push payment timeframes to the top of your list. In our comparison, time to funds ranges from next business day (QuickBooks) to 5+ business days (Finix). Helcim deposits 3–5 business days after the daily batch closes.
Do you need versatile billing options?
Versatile billing options include invoicing, email and SMS payments, and not every ACH payment processor gives you the ability to use the whole gamut. This is important, because some businesses - like healthcare clinics - find that not every customer likes to pay the same way. And research shows that payment options affect loyalty: in a 2023 survey of 300 business buyers, 72% said they’re more loyal to businesses that offer their preferred payment methods.
In our comparison, only Helcim and Square offer both email and SMS payment requests alongside built-in invoicing. GoCardless has no built-in invoicing, and Stripe, QuickBooks and Finix rely on email or a link you send yourself.
And card acceptance belongs on this list too. If your ACH provider only supports bank payments, you risk losing customers who’d rather pay by card. You’d also need a separate card processor, which means another tool in your tech stack and another set of monthly fees to manage.
How price sensitive are you?
The total cost of an ACH payment processor comes down to three things: the size of your payments, any monthly or plan fees, and the add-ons your billing setup triggers. The headline rate is only the starting point.
Payment size matters because of fee caps. Once payments pass about $1,000, most capped ACH processors stop charging more, while uncapped ones keep climbing. On a $10,000 payment, Helcim charges $6 and GoCardless and Stripe charge $5, but Square’s Free plan and QuickBooks charge $100.
Monthly fees and add-ons can also change the math quickly. Square charges $49/mo for its capped plan, QuickBooks charges $38/mo for unlimited invoicing ($85/mo for recurring billing) and Finix charges a $250/mo membership. Stripe and Finix also add 0.4% to every paid invoice, while Helcim and Square include invoicing for free.
Here’s what that looks like for a business collecting $125,000 a month by ACH payments (50 payments of $500 and 10 payments of $10,000):
| Provider | Monthly cost |
|---|---|
| GoCardless Standard | $177.50 |
| Helcim | $197.50 |
| Stripe | $250.00 |
| Square Plus | $399.00 ($350 + $49/month) |
| Finix | $615.00 ($365 in fees + $250/month) |
| QuickBooks Payments | $1,288.00 ($1250 in fees + $38/month) |
One-time payments, with no invoicing or recurring add-ons.
GoCardless comes out cheapest on ACH alone. Helcim is a close second and includes card payments and free invoicing in the same account, at a fraction of what the uncapped options cost.
Before you choose, add up a typical month: your usual payment sizes, any plan fee and the add-ons your billing setup needs. The cheapest rate on paper isn’t always the cheapest month.
Do you need card payments as a backup?
ACH payments can fail after the fact (e.g. insufficient funds) and when they do, you may want to have a card payment set up as a backup. Without this failsafe, you can find yourself chasing the payment while also paying your processor for the return fee ($4-$5, depending on the provider).
In our comparison, Helcim, Stripe, Square, QuickBooks and Finix all accept cards and ACH in one account. GoCardless doesn’t accept cards at all, so a failed ACH payment means arranging another way for your customer to pay.
What kind of support do you need?
When an ACH payment goes wrong, you need answers: a return you don’t recognize, a deposit that’s late or a payment you need traced. How quickly you get them depends on how your processor handles support, and the options vary a lot.
Each setup has trade-offs:
- 24/7 support is useful if you process payments around the clock.
- Business-hours phone support with real people usually means faster, clearer answers during the day, especially for problems like returns and payout holds.
- Chatbots can handle simple questions, but they add a step before you reach someone who can look into your account.
- Email-only support means waiting on a reply, which is hard when money is missing.
Think about when your problems are most likely to happen, and how long you can afford to wait for an answer.
FAQs:
Which ACH processor is best for recurring payments?
GoCardless has the lowest recurring rate. Helcim is the pick if you want cards as a backup and free invoicing in the same account. Here’s what a $500 recurring payment costs with each provider:
| Provider | Per payment | Monthly fee |
|---|---|---|
| GoCardless Standard | $2.55 | $0 |
| Helcim | $4.75 | $0 |
| Square | $5.00 | $0 |
| QuickBooks Payments | $5.00 | $85 (plan needed for recurring) |
| Finix | $7.25 | $250 |
| Stripe | $7.50 | $0 |
Which ACH processor is best for developers?
Most businesses don’t need a developer to accept ACH, since built-in invoicing, payment links and hosted payment pages work without code. Stripe and Finix are built for developer-led checkouts. Helcim also offers public APIs at no extra cost. Finix, in particular, is aimed at software platforms that process payments on behalf of other businesses.
What is the cheapest ACH processor?
GoCardless Standard is cheapest per payment ($2.55 on a $500 payment). Helcim is the lowest total cost once you need cards or invoicing. On large payments, providers with fee caps (Helcim, GoCardless, Stripe) cost far less than 1% uncapped options. Before choosing on price alone, add up monthly fees and add-ons, since those can outweigh a lower per-payment rate.